Skip to content
Home » BALTIC DRY INDEX

BALTIC DRY INDEX

Typographic illustration of a bulk carrier amid swirling global dry bulk market data, freight routes, rates and directional arrows

Dry bulk at a standstill: a market searching for direction

Dry bulk markets searched for direction as Capesizes weakened and smaller segments firmed during the week ending 11 September 2026, with regional tonnage – cargo balances increasingly shaping freight outcomes
Low-angle view of a large dry bulk carrier sailing in coastal waters beneath a dramatic cloud-filled sky, with mountainous shoreline visible in the background

Dry bulk market stuck in neutral as freight momentum fades

Drawing on market data from the week ending July 31, 2026, the dry bulk market remained largely range-bound, with larger vessel classes posting marginal gains while smaller segments continued to struggle under weak demand

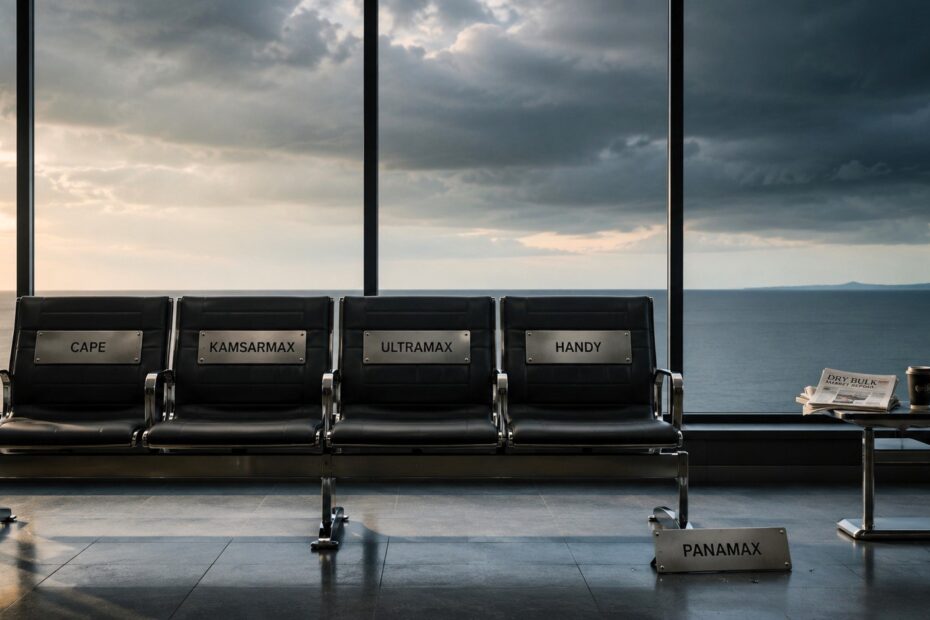
Minimalist airport-style waiting area with four seats labelled Cape, Kamsarmax, Ultramax and Handy, a fallen Panamax plaque on the floor, large windows overlooking a darkening horizon, and a newspaper resting on a nearby table

Calm before the storm: dry bulk market holds its breath

During the week ending 19 June 2026, dry bulk freight markets remained largely stable as owners and charterers waited for greater clarity on the evolving Iran–U.S. agreement, with Panamaxes providing the market’s main source of volatility

Close-up of a heavily weathered steel ship hull with extensive corrosion, peeling surfaces, riveted plates and jagged openings

Decks and Deals Weekly #46

The Strait of Hormuz reopened and then closed again this week as the United States and Iran signed a peace deal, while global shipping markets repriced freight, bunkers and sentiment, 14–20 June 2026