
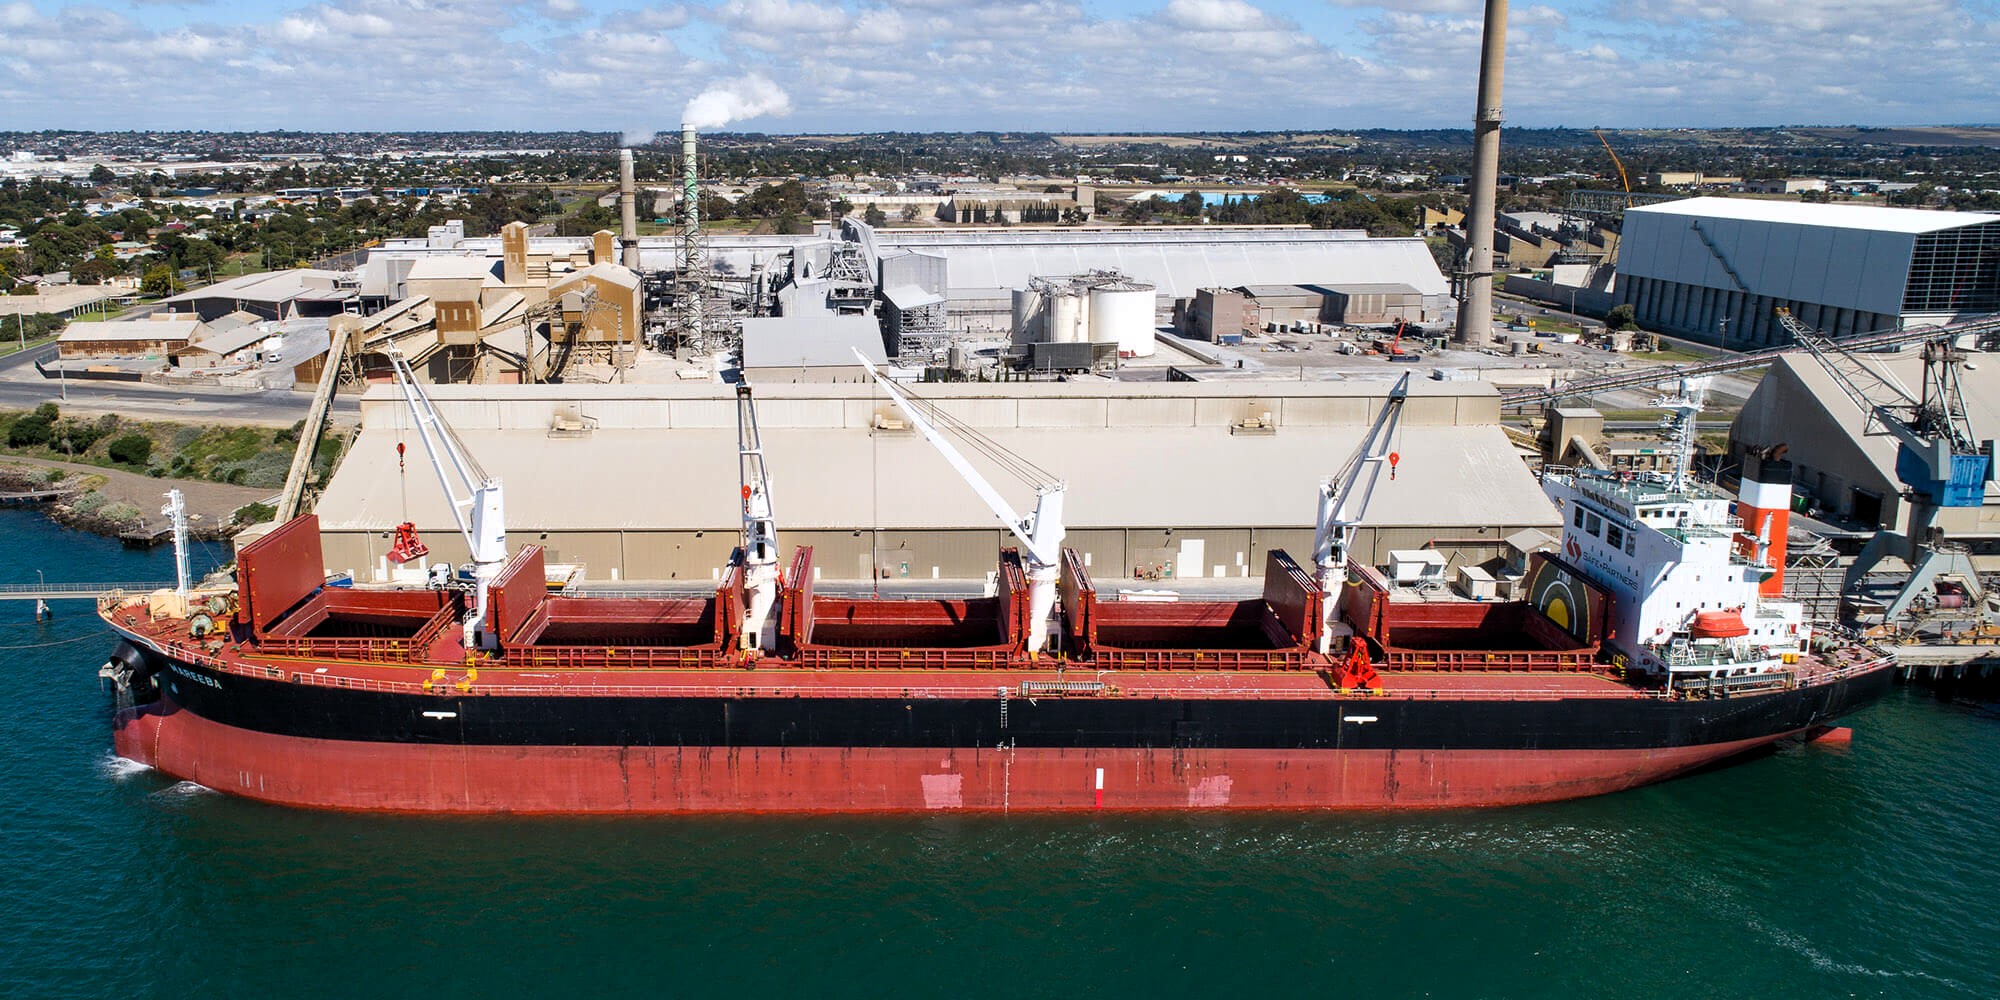

The dry bulk cargo market advanced last week, with the Baltic Dry Index (BDI) rising by 171 credits to close at 1,400 on Friday, March 7. This increase was primarily fueled by Capes, which recorded a strong 33.23% weekly rise. In contrast, Kamsarmaxes fell by 6.43%, Ultramaxes by 3.43%, while Handies remained in positive territory with a 1.64% increase.
Capesize market
Asia
The week started with gains on the main C5 route (Australia-China), but mid-week saw rates drop to single digits despite activity from the three major miners. By the end of the week, the market recovered slightly, closing at $10.1/tn.
Atlantic Basin
In the south, demand for April cargoes from Brazil and West Africa to China increased. Northern regions also saw high activity, with reduced vessel supply and rising transatlantic rates. By Friday:
- C3 (Brazil-China) route: $22.72/tn
- C9 (Continent-Asia) route: $37.28K/day
- C8 (Transatlantic round trips): $16.93K/day
Kamsarmax market
Atlantic Basin
Cargo flow slightly improved, but rates remained unchanged. Indicative rates:
- ECSA-Far East: $12.5-13.5K/day + $250-350K BB (delivery Latin America)
- Continent-Asia: $12.5-14.5K/day (delivery in Continent)
- Transatlantic round trips: $5-7K/day (delivery in Gibraltar)
Asia
A downward trend continued due to weak demand from Indonesia, Australia, and the North Pacific. The sharpest decline was in China-Indonesia round trips:
- Indonesia-Far East round trips: $7-9K/day (delivery in Far East)
Supramax-Ultramax market
Southeast Asia & Far East
A slow start saw limited demand, particularly for Indonesian coal cargoes. Rates:
- SE Asia-Far East: $10.5-12K/day
- North Pacific round trips: $9.5-11K/day
- W. C. India trips: $11.5-13K/day
- Atlantic Basin return trips: $12.5-14K/day
Middle East Gulf & W. C. India
Rates remained stable, though a potential recovery from South Africa may absorb available capacity:
- Far East UMX: $9-10.5K/day (MEG-WCI)
- Short Middle East Gulf-WCI: $7.5-9K/day
- Atlantic Basin trades: $5-6.5K/day
Atlantic Basin
The U.S. Gulf saw uncertainty due to U.S.-China tensions but retained a satisfactory cargo volume:
- Transatlantic trips: $13-14.5K/day
- Trips to Asia: $14.5-16K/day
In ECSA, early March cargoes held steady, while later cargoes declined due to increased vessel availability:
- SE Asia-China: $18-19.5K/day
- Transatlantic (Med/Continent): $16.5-18K/day
Europe
In the Continent, a gap between shipowners’ and charterers’ rates slowed activity. Scrap cargoes to the Eastern Med offered a slight premium:
- Round-local trips: $12-13.5K/day
- Scrap trips to the Med: $12-13.5K/day
- Trips to Asia: $15-16.5K/day
The Mediterranean market weakened mid-week due to oversupply:
- Med-Asia: $12-13.5K/day (Canakkale delivery)
- Med-Atlantic: $6.5-8K/day
- Intra-Med: $8.5-10K/day (excluding war zones)
Handysize market
Europe
The Continent remained stable despite increased cargo volume. Anticipation of more vessel supply led shipowners to hold back:
- Round trips: $12.5-14K/day
- Scrap to Med: $12.5-14K/day
- Transatlantic: $8.5-10K/day
The Mediterranean saw slight gains, with premiums on mineral and grain cargoes:
- Intra-Med: $6-7.5K/day (Canakkale delivery)
- Med-Continent: $6-7.5K/day
- Med-Atlantic: $6-7.5K/day
- Med-Asia: $10-11.5K/day
Atlantic Basin
The U.S. Gulf experienced solid cargo flow, though a long vessel list caused concern:
- Transatlantic trips: $10.5-12K/day
- Trips to Asia: $12.5-14K/day
ECSA remained steady, but vessel oversupply in West Africa raised concerns:
- Transatlantic (Continent-Med): $13.5-15K/day
- ECSA-Asia: $12.5-14K/day
Asia
A slow start in March gave way to increased activity from Australia mid-week. In the north, a vessel shortage supported rates:
- Far East/NOPAC round trips: $8-9.5K/day
- SE Asia-China: $8.5-10K/day
- W. C. India-China: $6-7.5K/day
Disclaimer
This report is for general informational purposes only and does not constitute investment advice.